CEO/Broker | NMLS: 304737
The short version: Your rate is fixed. Your property taxes and insurance aren't. When taxes rise, your escrow account comes up short, and your payment often goes up twice in the first year: once to cover the shortage and once to cover the higher bill going forward. Johnson County tax bills arrive in November, so now's the time to get ahead of it.
"My rate is locked. Why did my payment just go up $100?"
I hear this every winter. It's one of the most common, and most stressful, calls I get. The good news: it's almost always escrow, and it's almost always explainable.
Most mortgage payments are PITI:
When taxes or insurance go up, the escrow portion of your payment goes up with them. Your rate never moved.
In Kansas, residential property is assessed at 11.5% of its appraised market value. Your tax is that assessed value times the combined mill levy, divided by 1,000.
Here's the county, parks and library slice for 2027, using the Johnson County Post's example:
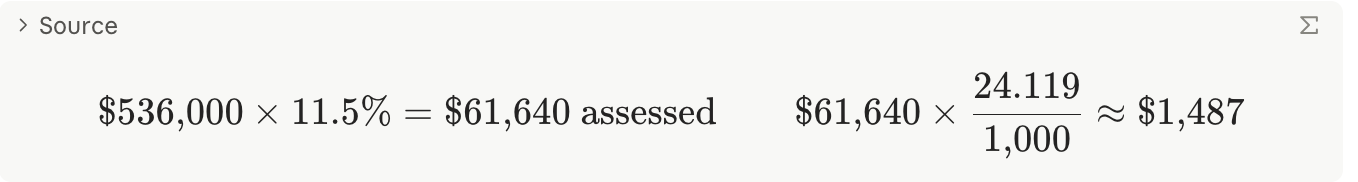
That works out to about $277.50 per $100,000 of value. And that's only part of the bill. Your school district, your city and other districts levy their own taxes, and together those make up most of what you pay.
Flat rate doesn't mean flat bill. The county's 2027 mill rate is essentially unchanged. But if your home's appraised value rose 5%, from $510,500 to $536,000, that same slice goes from about $1,416 to $1,487. Every other levy on your bill rises the same way.
Once a year, your mortgage company runs an escrow analysis. Federal rules (RESPA) set how it works:
Say your total tax bill rises $600 for the year:
Change in year one | Effect on monthly payment |
|---|---|
Higher projected bill going forward ($600 ÷ 12) | +$50 |
Repaying last year's $600 shortage over 12 months | +$50 |
Total increase, year one | +$100 |
Year two (shortage repaid) | Back down to +$50 |
That's why the first-year jump often feels bigger than the tax increase itself.
If the shortage is one month's escrow payment or more, your servicer has to let you spread it over at least 12 months. Most will also let you pay it in one lump sum. Paying it in a lump sum removes that part of the increase, leaving only the higher projected bill.
A surplus works in your favor. If it's $50 or more and you're current on your loan, your servicer has to refund it within 30 days.
Date | What happens |
|---|---|
On or before March 1 | Appraised value notices mailed. The informal appeal window opens |
November | Tax bills mailed |
December 20 | First-half taxes due, and the payment-under-protest deadline if you pay your own taxes |
January 31 | Payment-under-protest deadline if your mortgage company pays your taxes |
Early in the year | Many servicers send the escrow analysis reflecting the new bill |
If you didn't file an informal appeal this spring, Johnson County lets you file a payment under protest. You're allowed one protest per tax year, either an informal appeal or a payment under protest.
Outside Johnson County, every county runs its own calendar. Check your county assessor's site for the deadlines where you live.
Why did my mortgage payment go up if I have a fixed rate? Your principal and interest are fixed, but property taxes and insurance paid through escrow can change. When they rise, your servicer adjusts your monthly escrow payment.
What is an escrow shortage? It's when the escrow account didn't collect enough to cover the actual tax and insurance bills. Your servicer lets you repay it over at least 12 months, and usually lets you pay it in one lump sum instead.
When are Johnson County property tax bills mailed? In November. The first half is due December 20.
Can I still appeal my Johnson County property value? If you didn't file an informal appeal in the spring, you can file a payment under protest. The deadline is January 31 if your mortgage company pays your taxes, or December 20 if you pay them yourself.
Can I get rid of escrow? Sometimes. Conventional loans may allow an escrow waiver with enough equity, often 20% or more, and sometimes for a fee. FHA loans require escrow. Ask your loan officer what applies to you.
Disclaimer: This article is for educational purposes only and isn't tax or legal advice. Property tax rules and deadlines vary by county; confirm dates with your county appraiser. Planted Local Lending, NMLS 2430855 · Trish Reedy, NMLS 304737 · Equal Housing Lender.
CEO/Broker
Planted Local Lending | NMLS: 304737
